The letter from your insurer’s attorney asks you to appear on a specific date “for an examination under oath,” bring three years of bank statements, and expect a court reporter. Your claim is for a kitchen fire. You haven’t done anything wrong, so why does this feel like a lawsuit?
An examination under oath (EUO) is a formal interview your insurer is allowed to require under most property insurance policies. You answer questions about the loss under oath, a court reporter records everything, and the transcript becomes part of the claim file. Insurers often use EUOs on large, unusual or disputed claims. Taking it seriously, and preparing well, protects your claim.
What is an examination under oath?
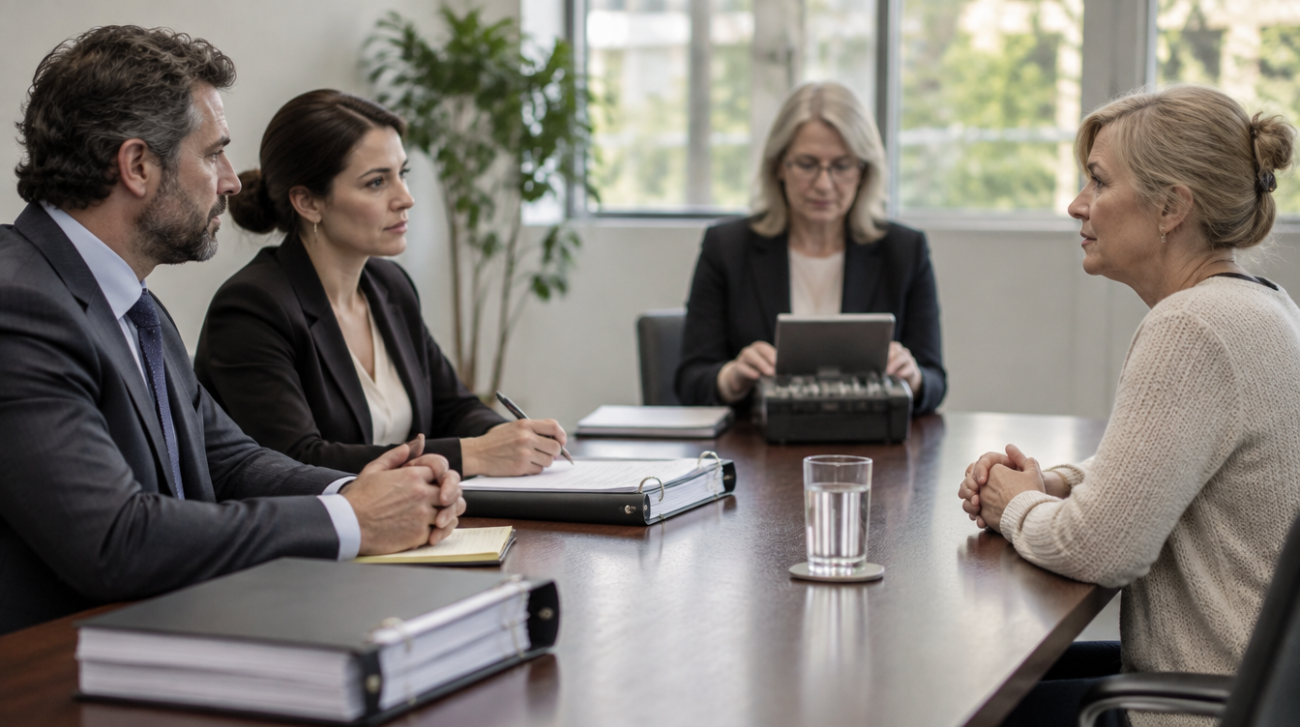
An EUO is a formal proceeding where the insured answers questions from an insurance company representative under oath, with a court reporter present (Claims Journal). The questioner is usually an attorney hired by the insurer.
The right comes from your policy. The standard homeowners policy lists it among your duties after a loss, requiring you to “submit to examination under oath” and sign the transcript (PropertyCasualty360). Most property policies also let the insurer demand records and documents that support the claim.
EUO vs. recorded statement vs. deposition
| Recorded statement | Examination under oath | Deposition | |
|---|---|---|---|
| When it happens | Early in the claim, often by phone | During the claim investigation, before a decision | During a lawsuit |
| Who asks | The adjuster | Usually the insurer’s attorney | Attorneys for both sides |
| Under oath? | Usually not | Yes | Yes |
| Where the right comes from | Cooperation clause | Your policy’s EUO condition | Court rules |
| Your lawyer’s role | Optional | Can attend, but usually can’t object the way they would in court | Can object and question |
Why insurers request an EUO
The stated purpose is to get the information the insurer needs to process the claim. United Policyholders notes that insurers use the procedure to screen out fraudulent claims and test the policyholder’s account. Common triggers include:
- a large loss, such as a fire or a total contents claim,
- a theft or a fire with an unclear cause,
- gaps or inconsistencies between your statements, documents and the adjuster’s findings,
- financial stress that could suggest a motive, which is why insurers ask for bank and tax records (see why an insurer asks for tax returns), and
- a claim that is much larger than the insurer expected.
A request for an EUO is not an accusation. Plenty of honest claims go through one and get paid. Treat it as the insurer’s most detailed fact check.
What happens if you refuse or skip the EUO
This is the part people underestimate. Once the insurer properly requests an EUO, complying generally works as a condition you must meet before you can recover under the policy, and most courts hold that an explicit refusal defeats coverage (Claims Journal). In California, the insurer doesn’t even have to show it was harmed by the refusal before denying the claim (Property Insurance Coverage Law Blog).
Some states are a little more forgiving when a missed EUO wasn’t deliberate. New York courts, for example, may give insureds a chance to cure the problem when the noncompliance wasn’t willful (Property Insurance Coverage Law Blog). Don’t count on that. If the date doesn’t work, ask in writing for another date right away.
Your rights during an EUO
You have obligations, but the insurer has limits too:
- Relevant questions only. In California, an insurer may conduct an EUO only to get information that is relevant and reasonably necessary to process or investigate the claim (United Policyholders). Other states apply similar reasonableness standards through court decisions.
- Reasonable scheduling. You can ask for a date and place that work for you.
- Your own attorney. You can bring one. Their role is more limited than in a court deposition, but they can prepare you and protect your record.
- Your claim file first. United Policyholders recommends asking for all claim related documents from your insurer’s files before you answer questions under oath.
- Review the transcript. You’ll usually be asked to read and sign it. Correct genuine errors in writing.
Note that each insured may be examined separately. In California, spouses who are both insureds don’t have the right to sit in on each other’s EUO (Property Insurance Coverage Law Blog).
How to prepare for an examination under oath
- Read the request letter twice. Note the date, place, who must attend, and every document category requested.
- Confirm in writing. Agree to attend or propose another date promptly. Keep the correspondence.
- Get your claim file and policy. Request copies of your recorded statement, the adjuster’s notes and estimates, and the full policy.
- Gather the documents. Bring what was requested, organized and labeled. If a request seems overly broad or private, raise it in writing before the EUO rather than ignoring it.
- Review your timeline. Write down the key dates: when you bought the items, when the damage happened, who was home, when you called the insurer and contractors.
- Compare your earlier statements. Re-read your claim submission and recorded statement. If something was wrong, plan to correct it honestly.
- Consider an attorney. On a large claim or one where fraud seems to be suspected, a policyholder attorney is worth the cost.
On the day: how to answer questions
- Tell the truth. Misstatements under oath can void coverage and expose you to fraud allegations.
- Answer only the question asked. Short, direct answers. Don’t volunteer extra theories.
- Don’t guess. “I don’t know” and “I don’t remember” are acceptable answers when they are true. Estimates should be labeled as estimates.
- Ask for clarification. If a question is confusing, say so before answering.
- Take breaks. EUOs can run for hours. You can ask for a short break between questions.
- Don’t argue. Stay calm and polite even if questions feel personal.
Common EUO question topics
Expect questions in these areas:
- your background, household members and occupation,
- the property’s purchase, mortgage and any prior claims,
- the day of the loss: where everyone was, what you saw, who you called,
- the damaged items: when and where you bought them, how you paid, what they were worth,
- your finances: income, debts and recent changes, especially on theft and fire claims, and
- repairs: who inspected, who estimated, and any contractor agreements.
After the EUO
You’ll receive the transcript to review and sign. Read every page. Afterward, the insurer will usually decide the claim within your state’s deadlines, which you can check in our guide to how long an insurance company has to pay a claim. If the insurer has already sent a reservation of rights letter, the EUO is often the step that decides whether those concerns turn into a denial.
If the claim is denied or underpaid afterward, see our guide to claim denial reasons and how to respond.
Frequently asked questions
Can I refuse an examination under oath?
You can, but it is risky. In most states, refusing a properly requested EUO lets the insurer deny the claim, and in some states the insurer doesn’t need to show it was harmed by the refusal. If the timing or scope is a problem, negotiate in writing instead of refusing.
Do I need a lawyer for an EUO?
Not always, but it is wise on large claims, theft or fire claims with an unclear cause, or when the request letter asks for extensive financial records. A lawyer can prepare you, review document requests and attend with you.
How long does an examination under oath take?
It varies with the claim. Simple claims may take an hour or two. Large or complex claims can take most of a day, and the insurer may examine each household member separately.
Is an EUO the same as a recorded statement?
No. A recorded statement is usually an informal interview with the adjuster, often by phone. An EUO is a formal proceeding under oath, typically run by the insurer’s attorney with a court reporter, and the transcript can be used if the claim ends up in court.
What documents do insurers ask for at an EUO?
Common requests include proof of ownership and value for damaged items, repair estimates, bank statements, tax returns, mortgage records and phone records. Requests should relate to the claim. If one seems too broad, raise it in writing before the EUO.