Your insurer approved the roof repair, but the first check is thousands of dollars short of the estimate. The missing amount may be recoverable depreciation, not a denied claim. This guide shows you how to read the settlement, document the work, request the remaining payment, and avoid mistakes that can shrink it.
Quick answer: Recoverable depreciation is the portion of a covered replacement cost claim that an insurer initially withholds to account for an item’s age or condition. If your policy allows replacement cost payment, you can usually request that amount after repairing or replacing the damaged property and submitting the required proof within your policy’s deadline, subject to actual costs and coverage limits.
What is recoverable depreciation in an insurance claim?
When a replacement cost policy pays a covered loss in two stages, the first payment is often based on actual cash value (ACV). The insurer estimates the cost to repair or replace the damaged item, then subtracts depreciation for wear, age, or condition. The withheld part may be labeled recoverable depreciation, replacement cost holdback, or depreciation withheld on the claim estimate.
That amount is not automatically a bonus payment. You must satisfy the policy’s replacement requirements, and the final payment is generally tied to the amount actually spent on covered work. Some items or policies are settled on an ACV-only basis, with no recoverable amount. For the basic distinction, see our guide to actual cash value vs. replacement cost.
The California Department of Insurance residential property claims guide explains that replacement cost means replacing damaged property with comparable property without a depreciation deduction, while ACV includes depreciation. Your own policy and state rules control the details.
How the insurance depreciation holdback changes your check
Imagine a covered roof replacement with an insurer-approved replacement cost of $18,000. The estimate lists $4,000 of recoverable depreciation and a $2,000 deductible. The initial payment would be $12,000: $18,000 minus $4,000 minus $2,000. If covered repairs are completed for $18,000 and all policy conditions are met, the additional payment could be $4,000. Your $2,000 deductible remains your responsibility.
If the approved repair instead costs $16,500, do not assume the full $4,000 is owed. The insurer may cap its total covered payment at the actual repair cost minus the deductible, which in this example would be $14,500. With $12,000 already paid, the later payment would be $2,500. This is an illustration, not a promise of a particular settlement: line items, policy language, limits, and state law matter.
Find the numbers on your estimate
Look for columns marked RCV (replacement cost value), depreciation, and ACV. Also check the claim summary for a deductible, prior payments, and the net amount. A line item may show recoverable and nonrecoverable depreciation separately. Ask your adjuster for a written explanation if the totals do not reconcile.
Do not confuse a withheld depreciation amount with a separate wind and hail deductible. The deductible does not usually become refundable after repairs. Likewise, a roof surface payment schedule may limit the roof payout by age under an endorsement, even if other parts of the home have replacement cost coverage.
How to recover depreciation after repairs
The most useful first step is to read both the declarations and the full claim settlement letter. Confirm that the damaged item has replacement cost coverage and identify the exact instructions for claiming the holdback. Then use this workflow:
- Confirm the approved scope. Compare the insurer’s line items with your contractor’s written estimate before signing. If a covered item is missing, ask how to submit a supplement before assuming the holdback will cover it.
- Ask about the deadline in writing. Check when the clock starts, what must be completed, and whether proof of intent or an extension can preserve your rights. Do not rely on a generic online deadline.
- Complete covered work. Keep invoices that identify the property, work performed, dates, amounts charged, and payments made. Save receipts for materials and replacement items.
- Document the result. Take before-and-after photos and retain permits or inspection records when relevant. Match each document to a line on the insurer’s estimate.
- Send a clear request. Upload or email the documents through the insurer’s official claim channel. State the claim number and ask for the recoverable depreciation or replacement cost balance. Keep confirmation of submission.
- Check the final statement. Compare the additional payment with approved work and prior payments. Request a line-by-line explanation for any unpaid amount.
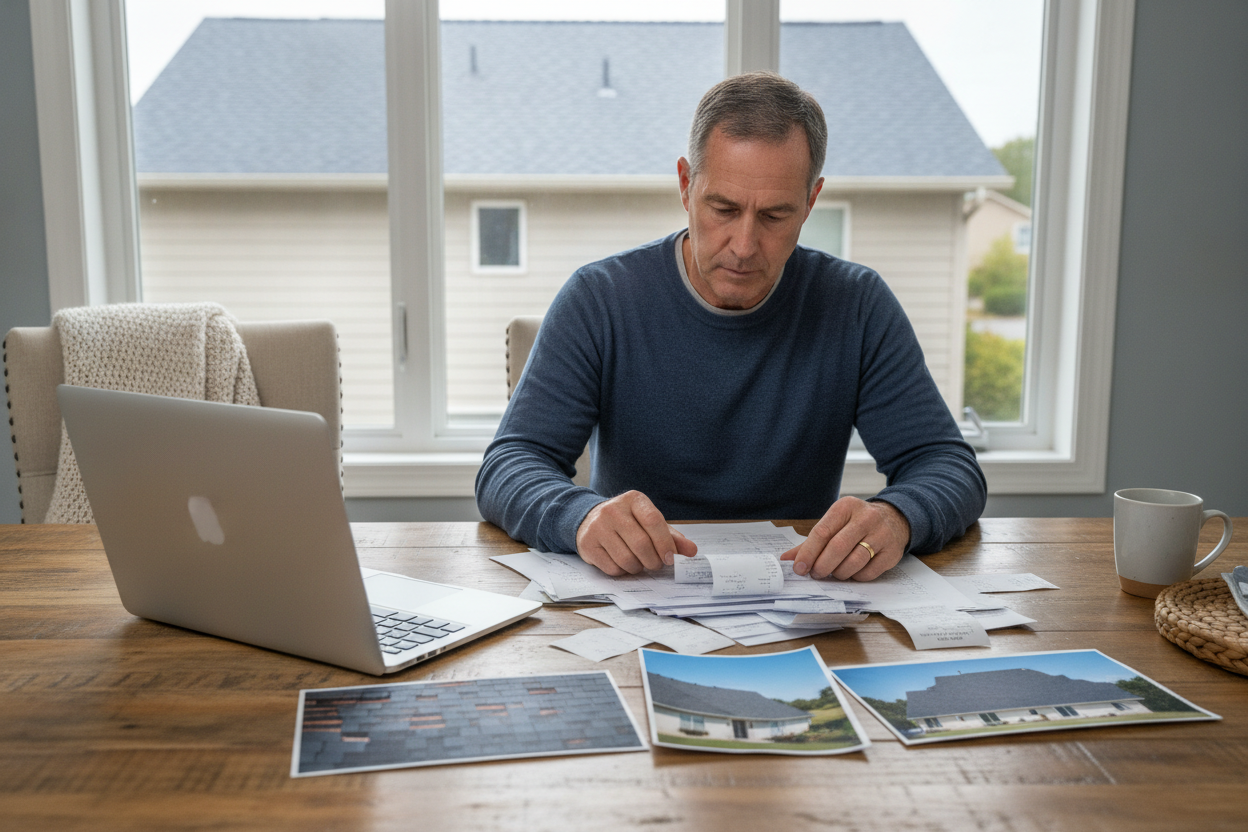
For a roof claim, a useful submission packet might contain the signed contractor agreement, final itemized invoice, proof of payment, completion photos, and permit sign-off if required. A paid deposit alone may not prove the roof was replaced. The carrier may ask for more documents or an inspection, so save your originals.
What if the contractor finds more damage?
Stop and photograph newly discovered damage before covering it up. Ask the contractor to write an itemized change order and discuss the additional scope with the adjuster. A request for an insurance claim supplement addresses covered work that was missing from the approved estimate; it is different from requesting depreciation already withheld on approved work. Do not assume the insurer will pay a higher invoice without approving the added scope.
Proof of repairs insurance companies may request
An estimate describes a proposed job; a final invoice shows what was billed. For a replacement cost claim, the insurer may need evidence that the work happened and what it actually cost. Give the adjuster a clean packet rather than a folder of unlabeled phone screenshots.
- Final itemized invoice: contractor name, service address, dates, materials, labor, total, and any change orders.
- Payment record: receipts, canceled checks, or transaction confirmations when requested.
- Completion evidence: dated photos, permit closure, or inspection report if applicable.
- Contents replacements: itemized store receipts showing what was bought, price, and date.
- Claim reference: claim number and a short cover note identifying the line items you want reviewed.
For personal belongings, a comparable replacement may be enough; a costly upgrade may not be reimbursed in full. The insurer may also treat building repairs and contents under different terms. Ask for the applicable provision if the documentation rules seem inconsistent with your policy.
Deadlines, cash flow, and common setbacks
A replacement cost claim can create a cash gap: the contractor may want a deposit before the withheld money is released. Ask for a written payment schedule tied to work milestones, and ask the insurer whether partial replacement cost payments are available as work progresses. Do not sign a contract requiring you to pay more than you can fund before the insurer confirms how it will handle the balance.
There is no single nationwide deadline. The timing can depend on policy wording, loss type, and state law, especially after a declared disaster. The Washington insurance commissioner’s homeowner guide describes how replacement coverage relates to the actual cost of covered repairs. For your claim, get the deadline and any extension decision in writing from the insurer and check with your state insurance department if the wording is unclear.
If the settlement check names your lender, that creates another process: the lender may endorse the check or release repair funds in stages. Follow the loan servicer’s loss draft instructions as well as the insurer’s claim instructions. Our guide to insurance checks made out to a mortgage company explains the separate endorsement steps.
When the holdback is smaller than expected
First compare the final paid invoice to the approved estimate, item by item. An inexpensive replacement, an unpaid deductible, an ACV-only endorsement, or work outside the covered scope may explain the difference. Ask for the precise policy provision and calculation in writing rather than accepting a vague statement that “depreciation was applied.”
If you disagree, send a concise written request for reconsideration with the estimate, final invoice, receipts, and photos. Keep a record of each contact. If the dispute remains unresolved, your state insurance department can explain complaint options; for a large loss, a licensed local professional may help you understand the policy and claim process.
Frequently asked questions
Do you always get recoverable depreciation back?
No. It depends on replacement cost coverage, policy conditions, proof that covered property was repaired or replaced, deadlines, and actual expenses. ACV-only settlements generally do not include a recoverable holdback.
Can I claim depreciation before repairs are finished?
Some insurers may make progress payments or accept certain proof of replacement, but do not count on an early release. Ask your adjuster what your policy requires and whether partial payments are available.
Is recoverable depreciation the same as my deductible?
No. Recoverable depreciation is a potentially payable withheld amount on eligible replacement cost claims. Your deductible is the share of a covered loss you agreed to pay and typically is not reimbursed.
What if I do not replace the damaged item?
You may keep the initial ACV payment for a covered loss, subject to your policy, but generally cannot collect the replacement cost difference for work you did not perform. Ask the insurer how any specific item will be settled.
Can I request more time to submit proof?
Ask promptly and in writing before the stated deadline. Extensions depend on your policy and applicable state law. Keep the insurer’s reply and ask your state insurance department about your rights if a disaster or repair shortage has delayed the work.
Your next step
Open your claim estimate today and highlight three numbers: replacement cost, recoverable depreciation, and deductible. Then ask the adjuster for the exact proof and deadline required for the remaining payment. If the scope itself is short, review the supplement process before paying a contractor for work the estimate does not yet cover. Share your question in the comments, but keep claim numbers and personal documents private.