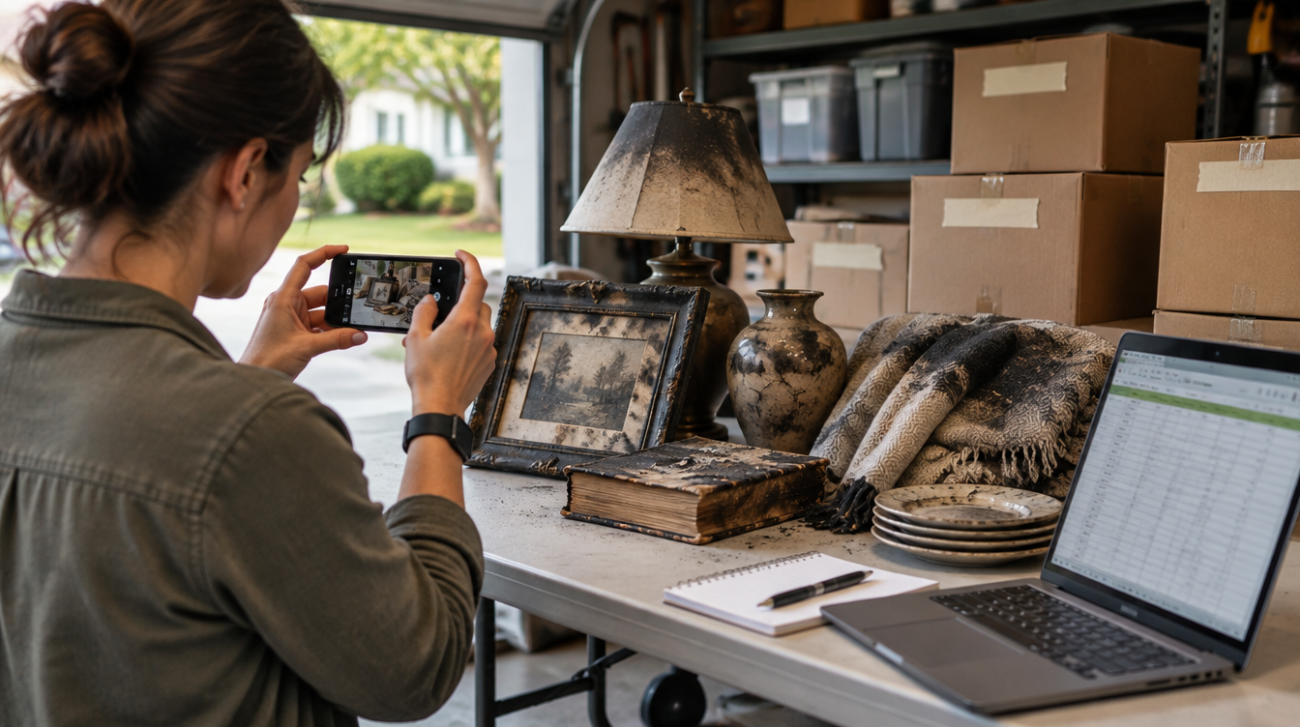
After a kitchen fire, the adjuster handles the walls and cabinets with a measuring tape and a software estimate. Then he hands you a spreadsheet template and says, “For your contents, list everything that was damaged, with age and price.” You stare at it and think about the hundreds of things in a single kitchen.
The personal property part of a home insurance claim, also called a contents claim or Coverage C, is often the slowest and most frustrating part. It is also where homeowners leave the most money on the table. A few smart choices about how you build the list, how you price it and how you push back on depreciation can make a large difference in what you collect.
What personal property coverage pays for
Coverage C pays for your belongings: furniture, clothes, electronics, kitchenware, tools, decor and other things you would take with you if you moved. Some items, like appliances, HVAC systems and carpeting, can fall under either the dwelling or the contents part of the claim depending on how they are installed (United Policyholders).
Before you start, check three things on your policy:
- Your Coverage C limit on the declarations page. That is the most the insurer will pay for all contents combined.
- Special limits on categories such as jewelry, firearms, cash and collectibles, along with any items you have scheduled separately (Property Insurance Coverage Law Blog).
- Loss settlement: whether you have actual cash value or replacement cost coverage for contents.
ACV, replacement cost and depreciation
Three terms decide how much you get (United Policyholders):
- Replacement cost value (RCV): the price of a new, comparable item today.
- Depreciation: the loss in value from age, wear and tear.
- Actual cash value (ACV): in most policies and states, replacement cost minus depreciation. Some states define it differently. In California, for example, United Policyholders explains that ACV is defined as fair market value (United Policyholders).
Even when you have replacement cost coverage, many policies pay only the actual cash value until you actually replace the item (Property Insurance Coverage Law Blog). The difference is recoverable depreciation, which you collect after you buy the replacement and send proof.
Example: how one item gets paid
Illustrative numbers for a sofa damaged in a fire:
| Step | Amount |
|---|---|
| Replacement cost of a comparable new sofa | $2,000 |
| Depreciation the adjuster applies (4 years at 10% a year) | minus $800 |
| First check (actual cash value) | $1,200 |
| Paid after you buy the replacement and send the receipt | $800 |
Your deductible usually comes off the claim once, not off each item.
How to build an inventory that gets paid
The standard process is to prepare a detailed list of every damaged or destroyed item, noting its approximate age, value and replacement cost (United Policyholders). Here is how to make that manageable:
- Go room by room. Work through one room at a time, including closets, drawers, the garage and the attic.
- Use every memory aid. Phone photos, social media posts, videos of birthdays and holidays, online order histories, credit card statements and store loyalty accounts. For a total loss, much of the list may have to come from memory (Property Insurance Coverage Law Blog).
- Don’t skip small items. Spices, cleaning supplies, linens, chargers and toiletries add up to thousands of dollars in a typical home.
- Record the basics for each item. Description, brand and model if known, quantity, age, where you bought it and the replacement price.
- Price with stable sources. Use a retailer’s regular price for a comparable new item. Avoid sources where prices swing wildly, such as auction listings or flash sales.
- Keep damaged items until the adjuster says otherwise. If you must throw things away for health reasons, photograph them first.
Sample inventory columns
| Room | Item | Brand / model | Qty | Age | Replacement cost | Source / link |
|---|---|---|---|---|---|---|
| Living room | Sofa, 3-seat fabric | Store brand | 1 | 4 yrs | $2,000 | Retailer listing |
| Kitchen | Stand mixer | Model name | 1 | 6 yrs | $400 | Retailer listing |
| Bedroom | Men’s dress shirts | Various | 8 | 2 yrs | $320 | Average price |
Push back on excessive depreciation
There is no agreed-upon schedule for how much insurers can depreciate your personal property. Adjusters use their own views plus their employer’s guidelines (United Policyholders). That leaves room to negotiate:
- Reject flat percentages. Push back if an adjuster depreciates everything by the same percentage across the board (United Policyholders).
- Point out condition. Lightly used items should be depreciated less. United Policyholders gives the example of guest room furniture, which was used less than master bedroom furniture.
- Some items shouldn’t depreciate much at all. For some items, replacement cost and actual cash value are the same.
- Ask for the depreciation schedule in writing. Then answer it line by line on the items that matter most.
Shortcuts after a total loss
If your home is destroyed, listing every item can take months. Two strategies can save time:
- Ask for an inventory waiver. After a total loss with relatively low contents limits, you can ask in writing for a waiver of the inventory requirement and a settlement of your contents limit (United Policyholders). Some insurers agree, especially after large disasters.
- Stop when you reach the limit. If reasonable actual cash values alone reach your Coverage C limit, you don’t need to track replacement purchases to collect the rest (United Policyholders). List your most valuable items first so you reach the limit sooner.
Ask for an advance on your contents coverage too. It helps you buy essentials while the full claim is pending. See our guide to getting an advance payment, and use your additional living expenses coverage for hotel and meal costs.
Submitting and tracking the contents claim
- Send the inventory with your proof of loss if your insurer requires one, and keep a copy.
- Ask the adjuster to confirm in writing which items are approved, how each was valued and how much depreciation was applied.
- Replace items as your budget allows and keep every receipt.
- Submit receipts in batches to collect the withheld depreciation, and track each batch.
- Check your policy for a deadline to replace items and claim the replacement cost. Ask for an extension in writing if you need more time.
Your insurer still has to follow state claim deadlines while all this happens. Our guide to how long an insurance company has to pay a claim covers the rules.
Frequently asked questions
Do I need receipts for a personal property claim?
Not for everything. Receipts help, but photos, videos, bank and credit card statements, order histories and your own detailed descriptions can all support a claim. Most people don’t have receipts for everyday items, and insurers know that.
How much does insurance pay for personal property?
Up to your Coverage C limit, minus your deductible. With actual cash value coverage you receive the depreciated value. With replacement cost coverage you usually get the depreciated value first and the rest after you replace items.
Can I negotiate depreciation on my contents claim?
Yes. There is no standard depreciation schedule, so you can challenge flat percentages and argue for lower depreciation on items that were new, lightly used or well kept.
What if I can’t remember everything I owned?
Use photos, videos, social media, online order histories and statements to jog your memory, and go room by room. After a total loss, ask the insurer in writing whether it will waive the full itemized inventory and settle the contents limit.
How long do I have to replace items to get full replacement cost?
It depends on your policy and your state. Many policies set a deadline for replacing items and claiming the withheld depreciation. Read that section of your policy and ask for an extension in writing if you need one.